

Money App - Cash Advance
4.0

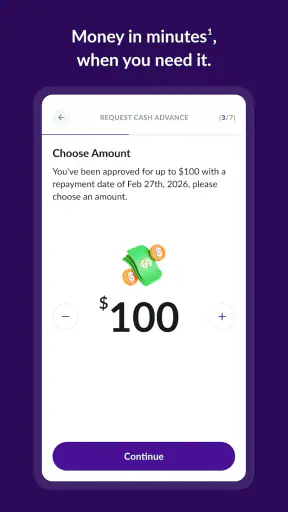
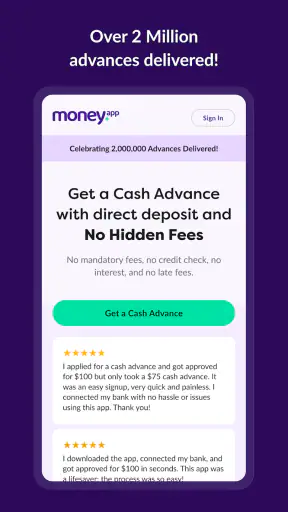
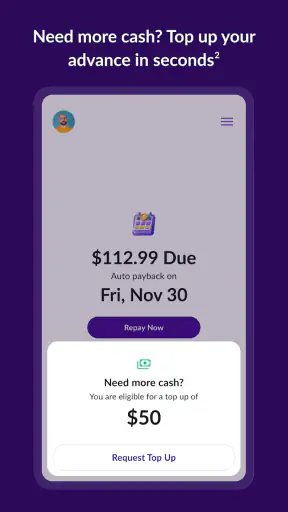
When I’m short before payday, I want to know what a cash-advance app can actually help with—and what it can’t. Money App - Cash Advance is a finance app from PRG Ventures, built around access to emergency cash. Its appeal is easy to understand, but I’d treat it as a possible bridge for a temporary gap, not as extra income or a routine way to stretch a budget.
What the current version tells me
The app is currently at version 2.41.1 and was released on February 12, 2024. Those details give a useful point of reference for someone deciding whether to install it: there is a current version to assess, but a version number by itself does not tell me which features changed, how the service has evolved, or what an existing user will notice after an update. I’d separate that confirmed snapshot from any expectations about future improvements.
Money App is free to download, carries an Everyone age rating, and has a 4.0 average from around 8.7 thousand ratings, with about 2.2 thousand written reviews and over 100 thousand installs. That level of uptake suggests it has reached a meaningful audience, but popularity isn’t a substitute for checking whether its terms and eligibility fit your circumstances. I’d read the in-app details before relying on an advance.
Where it fits in a tight week
The clearest use case is a short-lived cash-flow mismatch: an essential bill arrives before the next paycheck, and waiting would create a more immediate problem. For example, if a necessary household expense falls due a few days before payday, an eligible user might consider whether an advance can cover that timing gap. The key word is “might”: eligibility, the amount offered, and the timing of access can affect whether it solves the problem in time.
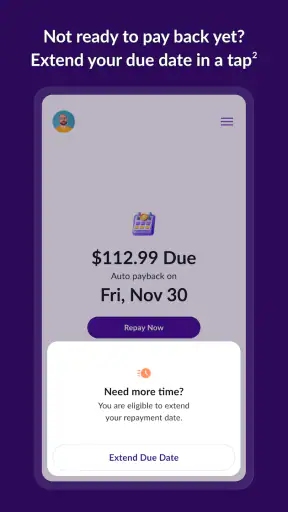
I would first write down the expense, the amount required, and the date I expect money to arrive. Then I’d compare the repayment timing and full cost shown in the app with that date. That small check matters because an advance can move pressure from this week into the next one. If repaying it would leave too little for rent, food, transport, or another fixed bill, the app may postpone rather than solve the shortfall.
This is why I see a cash advance as a narrow tool, not a budget plan. It may be relevant for someone with a temporary timing issue and a realistic way to repay. It is a poor fit for a recurring monthly deficit, an uncertain payday, or an expense that cannot safely be covered from the next income cycle. In those situations, asking a bill provider about a payment arrangement or talking through options with a trusted local adviser may be more useful than borrowing against money already expected.
Comparing it with familiar alternatives
Compared with a credit card, an advance app is aimed at a paycheck-linked cash gap rather than ongoing purchases. A credit card may be more convenient for a merchant payment, while cash in a bank account can be more flexible once received. But the right comparison is not simply “which is faster?” It is the full cost, repayment date, and consequences of using each option. I would not assume an app advance is cheaper or easier to qualify for than a card; I’d compare the terms actually offered to me.
A personal loan is usually considered for a larger or longer repayment need, while a cash-advance app is more naturally suited to a smaller, short-term bridge. Neither label makes borrowing harmless. If the need is substantial or will last beyond one pay cycle, it is worth comparing options that show the total repayment clearly and allow a realistic schedule. If the expense is discretionary, delaying the purchase may be the least costly alternative.
There is also a practical alternative people overlook: contact the person or company expecting payment before the due date. A conversation about moving a due date or splitting a bill may avoid borrowing altogether. That won’t work for every expense, but it is worth checking before opening an advance request, especially when the next paycheck is already committed to essentials.
Using the app without creating another crunch
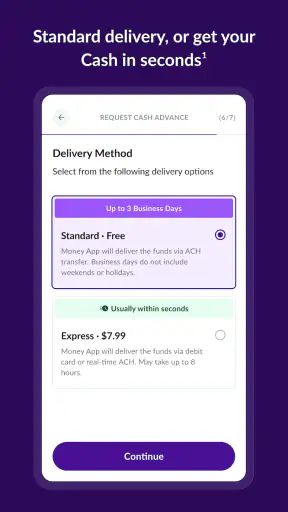
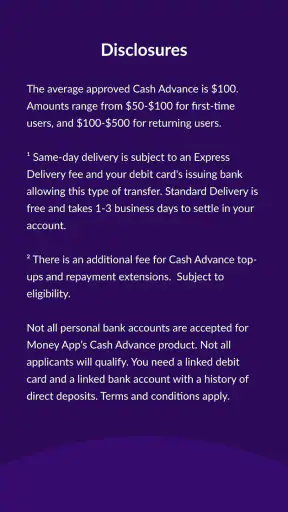
Before requesting money, I’d treat the screen showing the offer as a decision point rather than a green light. Confirm how much would arrive, what repayment is expected, when it is due, and whether any optional costs or terms apply. If anything is unclear, I would pause rather than infer the answer from a short summary. A useful habit is to check the repayment against a simple list of next-payday obligations, not just the account balance today.
One non-obvious trade-off is that a quick solution can make a recurring pattern harder to see. If the same shortfall happens each month, note the dates and categories behind it—such as bills clustering before payday or irregular costs that are predictable over a longer period. That record can show whether changing a due date, setting aside a small amount when income arrives, or revisiting a budget would address the cause better than taking another advance.
Another helpful step is to decide in advance what counts as an emergency for you. A necessary repair or essential bill may justify considering a short bridge; an impulse purchase usually does not. Setting that boundary before a stressful moment makes it easier to avoid using an advance just because the option is available. I’d also avoid treating a possible approval as guaranteed money until the app has actually confirmed the request.
Bank linking is a meaningful point of friction for some people. Before connecting an account, I’d read the permission and security information presented in the app and consider whether I’m comfortable with the access requested. The earlier article’s reassurance about encryption and safety measures should not replace that personal check: security claims do not answer every practical question about what information is accessed or how account connections work. If you are uncomfortable linking a bank account, this may not be the right service for you.
Who is likely to find it useful
I can see the app being most relevant to someone who has a clear, one-off timing gap, can review the terms calmly, and expects enough income to repay without missing another essential expense. The fact that it is free to download removes an upfront app purchase, but that alone does not establish the cost of borrowing. I would judge the offer by its displayed repayment details, not by the word “free.”
It is less suitable for anyone who needs certainty that a particular amount will be available immediately, cannot comfortably meet the repayment date, or is already relying on advances to cover normal monthly spending. Someone who prefers not to share bank-account access should also weigh that concern before proceeding. For longer-term debt or a larger planned expense, comparing established borrowing options and speaking with a qualified adviser may be a better route.
New users may also want to know whether applying guarantees an advance. It does not make sense to plan around money before an offer is shown and accepted; review the app’s eligibility and request details directly. Similarly, the arrival time matters as much as approval if a bill is due soon, so check the timing displayed for your own request rather than building a plan around a general expectation.
What existing users should watch
For someone already using the app, a version change is a reason to review the screens and terms that matter to their next decision, not a reason to assume the service has changed in a particular way. The current version number offers a snapshot, but it does not, on its own, establish a feature history. I’d check the app’s current explanations whenever requesting an advance and keep a personal record of the requested amount, expected repayment, and date.
That record can be as simple as a note in a calendar. It helps prevent a repayment from surprising you and makes it easier to see whether using the app is occasional or becoming routine. If the repayment schedule or terms shown at the time differ from what you expected, stop and resolve the discrepancy before continuing. For a finance app, clarity at the point of commitment matters more than a polished interface.
What I would watch over time is whether the service makes the total obligation easy to understand before a request is finalized, and whether the timing suits a user’s actual pay cycle. Those are practical standards, not predictions about future releases. A newer version would be valuable to existing users only if changes improve decisions or reduce friction without obscuring what repayment means.
Have you ever found yourself in a pinch, needing a quick cash boost to get through the week? Well, let me tell you, Money App - Cash Advance might just be your new best friend. I gave it a whirl to see if it lives up to the hype, and here's everything you need to know about this potentially life-saving app.
First Impressions
Downloading the Money App - Cash Advance was a breeze. It’s available on both Android and iOS, so no one’s left out in the cold. Once you fire it up, the user interface greets you with a sleek, no-nonsense design. It's clear that the developers wanted to keep things simple, which is a big plus in my book. You don’t want to be bogged down with complicated menus when you’re trying to sort out a financial jam.
Setting Up
The setup process is straightforward. You start by creating an account, which involves entering some basic personal information. Don’t worry, they keep your data secure with encryption and other safety measures. Linking your bank account is the next step, which might make some folks a bit uneasy. But from what I’ve seen, the app goes the extra mile to ensure your information stays safe and sound.
Features Galore
This app isn’t just about getting quick cash advances. It packs a punch with a host of other features that aim to make your life easier. Need to track your spending? Check. Want to manage your budget better? Done. It even offers personalized financial advice, which is like having a tiny financial advisor in your pocket.
"It’s like having a financial safety net, right in your pocket."
The cash advance feature is the real star of the show, though. You can request a small advance on your paycheck, which is a lifesaver when unexpected expenses pop up. The terms are transparent, and they don’t hit you with hidden fees, which is refreshing.
Using the Cash Advance
Requesting a cash advance is as easy as pie. You select the amount you need and submit your request. They review it quickly, and voila! The cash is in your account, usually within a day. It’s perfect for those "just in case" moments when your car suddenly decides it doesn’t want to start, or you spot a surprise bill in the mail.
- Fast and easy request process
- No hidden fees
- Quick approval and transfer
Final Thoughts
So, is Money App - Cash Advance worth it? If you’re someone who occasionally finds themselves in need of a little financial flexibility, then absolutely. It’s not a substitute for a solid financial plan, but it sure is a handy tool to have when life throws you a curveball. The app is user-friendly, secure, and best of all, it delivers on its promises without any sneaky surprises.
Don’t just take my word for it. Give it a try and see how it fits into your financial toolkit. After all, it’s always nice to know you’ve got a little backup when you need it most.
4.0
2.17K Reviews
Pros
- Quick and easy cash advances.
- No credit check required.
- User-friendly interface.
- Fast approval process.
- Flexible repayment options.
Cons
- High interest rates.
- Limited withdrawal amounts.
- Requires bank account link.
- Not available in all regions.
- Frequent app notifications.


